Can a leaking roof be claimed on insurance in North Carolina?
Sometimes. An insurer looks at what caused the leak and at what your policy covers, and you can usually work out which way a claim will go before you file it.
The short answer
A homeowners policy in North Carolina covers direct physical damage, according to the state Department of Insurance. A leak can be part of a claim when something happened to the roof: wind lifted or tore off shingles, hail damaged them, or a limb came through the decking. A leak from a part that wore out over time, like a pipe boot cracked by years of sun, has no storm or event behind it. Whether a policy pays anything toward that comes down to its own wording, so read the exclusions section or ask your agent before you file.
Check your policy for these first
- Whether wind and hail are covered at all. The Department of Insurance notes that an insurer’s underwriting rules can mean a homeowners policy excludes windstorm or hail damage, and it tells homeowners to review the policy with their agent.
- Your deductible. It is on the declarations page. Some policies carry a separate wind, hail or named-storm deductible, and a wind or hail deductible can be a percentage of your dwelling coverage instead of a flat amount.
- Actual cash value or replacement cost. With actual cash value coverage you receive the depreciated amount, meaning the repair cost minus the loss in value from age and use. Replacement cost coverage reimburses the repair at today’s cost.
- Flood. Homeowners policies do not cover flood or rising water. If the water came up from outside rather than down through the roof, that is a flood insurance question, handled through the National Flood Insurance Program.
Our post on how long you have to file a roof claim in NC goes further into the deductible and the timing.
How to tell what caused the leak
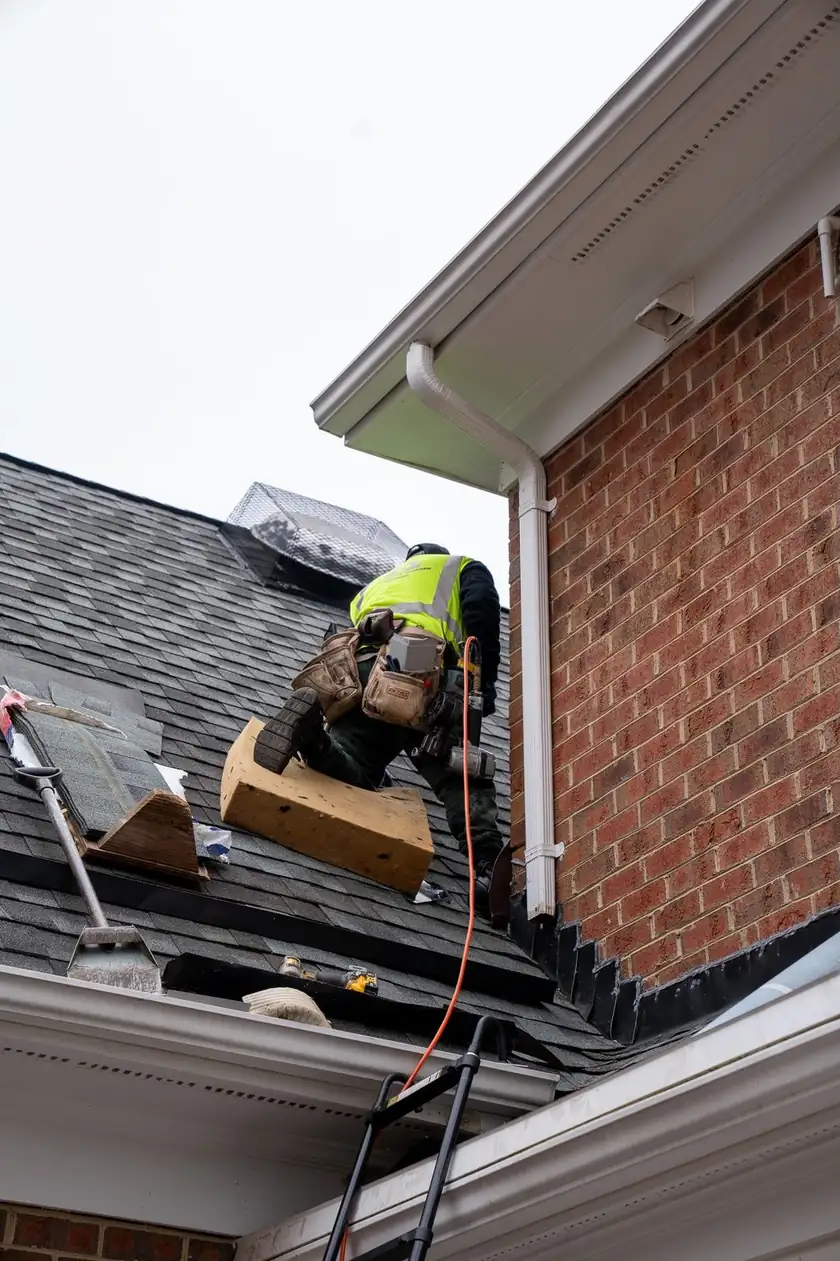
The ceiling stain cannot settle it. The cause shows up on the roof and in the attic. After a wind event that means torn or creased tabs along the ridge and the rakes. After hail, look for bruised shingles and dents in vents and gutters, and after a tree comes down, a broken limb and a hole in the decking. Wear looks different: a pipe boot with a split collar, caulk cracked and pulled away from flashing, or shingles worn bald across a whole slope.
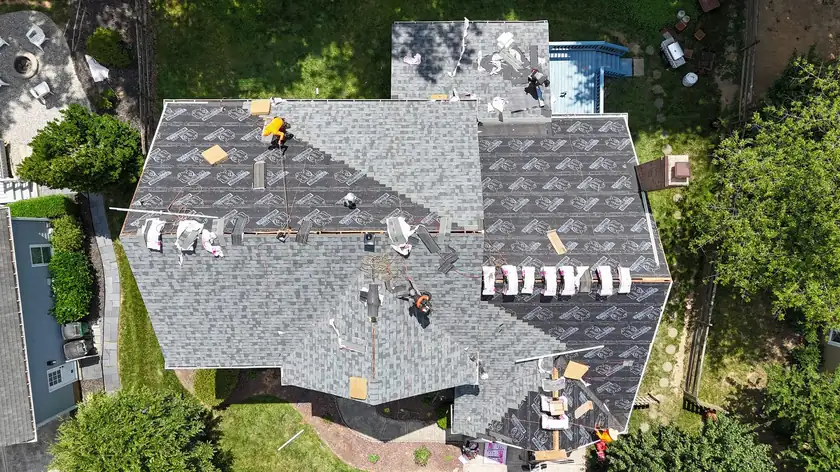
That is why the photos matter. At the free inspection our owner photographs the slopes, the flashing and the attic side of the leak, and you keep the pictures. Two of our Google reviewers had damage they had not noticed. For one, a storm the summer before had damaged the roof, and the drone photos from our inspection showed it; they called their insurance agent and the claim went from there. For the other, a free inspection turned up hail damage, and their insurance handled it. Those are their outcomes, and yours depends on your roof and your policy.
What North Carolina tells you to do after storm damage
For wind and hail losses, the Department of Insurance tells homeowners to report the loss to their agent or company, and to do what they can to stop further damage, such as a tarp on the roof. Reasonable expenses to protect the property may be reimbursed, so keep the receipts. List the damage and take clear pictures before any temporary repair, and hold off on permanent repairs until the insurer has inspected and you have agreed on the cost. Check with the insurer before you throw away damaged materials.
The insurer should acknowledge the claim within 30 days. There is no fixed time limit for settling it, since every claim is different.
What a claim pays for on the roof
The Department of Insurance answers the question “does the company have to replace my whole roof?” with a no. The policy covers direct physical damage, so the insurer only has to replace the damaged area, even if the new shingles will not match, and the original shingles may be discontinued. Our post on the 25% rule for roofing in NC explains why a quarter of the roof does not automatically mean a full replacement here.
A leak also leaves damage inside, like wet insulation and stained drywall. Whether that part is covered depends on your policy, so put it on your list and photograph it with the rest.
If the leak comes from age
Then it is a repair you plan and pay for. A minor one, such as a new pipe boot or a sealed flashing leak, may only take a few hours. Getting it done early keeps the water away from the decking and the ceiling, where a small leak grows into a bigger job. See roof repair in Charlotte for how we handle those, and our post on how to fix a leaky roof for what to do inside the house in the meantime.
Find out what caused your leak
We do a free photo inspection of the roof and the attic and show you what caused the leak. If it is storm damage, we photograph it for your adjuster and can meet the adjuster at the house. Read about storm damage roof repair in Charlotte, call (704) 352-1112, or request a free roof inspection.